Why Emerging Markets Are Leading the Next Wave of Fleet Electrification
The conventional assumption has been that fleet electrification is a developed-market phenomenon — driven by stringent emissions regulation, mature charging infrastructure and high consumer purchasing power. The evidence is beginning to challenge that assumption. Across Africa, South and Southeast Asia, Latin America and the Middle East, the conditions for rapid commercial fleet electrification are forming in ways that differ from the developed-market model but are no less compelling.
The story of electric vehicle adoption has, until recently, been told primarily as a developed-market story. Europe tightening emissions standards. North American states mandating zero-emission vehicle sales. East Asian manufacturers scaling production. The infrastructure, the policy frameworks and the purchasing power that drove early EV adoption were concentrated in economies that already had mature automotive markets and established regulatory institutions.
That framing is becoming less accurate. Across a broad range of emerging and developing economies, the conditions for rapid commercial fleet electrification are forming — not as a replication of the developed-market model, but as something structurally different and, in several respects, more compelling. The drivers are not primarily regulatory compliance or consumer preference. They are economic necessity, urban growth pressure, fuel cost volatility and the practical logic of fleet replacement cycles in markets where commercial mobility is expanding faster than conventional infrastructure can support it.
This article examines why emerging markets are increasingly positioned at the leading edge of the next wave of fleet electrification — and what the structural conditions driving that transition actually look like on the ground.
Section 1: Urban Growth as a Mobility Pressure System
The scale and pace of urbanisation in emerging markets has no equivalent in the developed world. Cities across sub-Saharan Africa, South Asia, Southeast Asia and Latin America are absorbing population at rates that strain every dimension of urban infrastructure — housing, water, energy, sanitation and, critically, transport.
The transport consequence of this growth is a rapidly expanding demand for commercial mobility services. As urban populations grow and spread across larger geographic areas, the need for affordable, accessible, on-demand transport increases proportionally. In cities where metro systems are still under construction, where bus rapid transit networks are incomplete and where private car ownership remains beyond the financial reach of most urban residents, taxis and ride-hailing services function as the primary formal mobility layer.
The density of commercial vehicle use in these urban environments is significantly higher than in developed-market cities. A taxi operating in a dense, rapidly growing emerging market city may cover substantially more kilometres per day than an equivalent vehicle in a European or North American city — driven by longer operating hours, higher passenger demand and the absence of competing mobility alternatives. This intensity of use has direct implications for fleet economics: the vehicles that serve these markets are working harder, consuming more fuel and generating more maintenance cost per unit of time than their developed-market counterparts.
The infrastructure gap that characterises many emerging market cities — incomplete road networks, variable traffic management, limited formal parking — creates operating conditions that are demanding on vehicles. Fleet operators in these environments have a strong practical interest in vehicles that are durable, low-maintenance and economical to operate, independent of any environmental consideration. These are precisely the characteristics that purpose-built electric commercial vehicles are increasingly able to deliver.
Section 2: The Fuel Economics Argument — Stronger in Emerging Markets Than Anywhere Else
The economic case for fleet electrification is built primarily on the difference between the cost of electricity and the cost of liquid fuel per kilometre of commercial operation. In developed markets, this differential is real but is moderated by relatively stable fuel prices, efficient conventional powertrains and established maintenance ecosystems for conventional vehicles.
In many emerging markets, the fuel economics argument for electrification is substantially stronger — for reasons that are structural rather than incidental.
Fuel price volatility is a defining feature of commercial fleet economics in markets that import petroleum products. Currency depreciation, global oil price movements and supply chain disruptions translate directly into unpredictable operating costs for fleet operators who depend on diesel or petrol. A fleet operator whose fuel costs can increase by a significant percentage within a single quarter — as has occurred repeatedly across various emerging markets — faces a planning challenge that electric vehicles, with their more stable and locally-determined energy costs, do not present in the same form.
Fuel subsidy reform in a number of emerging economies has removed or reduced the price support that previously made conventional fuel artificially affordable. As subsidies are withdrawn, the true cost of liquid fuel becomes visible in fleet operating accounts — and the comparative economics of electric operation improve correspondingly. Fleet operators who electrify ahead of further subsidy reform are better positioned than those who wait.
Electricity cost structures in many emerging markets, while variable in reliability, are often lower in absolute terms than liquid fuel costs per unit of energy delivered. For fleet operators who can access reliable grid power — or who invest in solar-supplemented depot charging — the energy cost per kilometre of electric operation can be meaningfully lower than conventional alternatives, even before accounting for maintenance cost differences.
Maintenance cost reduction is arguably the most immediately compelling economic argument for fleet electrification in emerging markets, where the cost and availability of conventional vehicle maintenance — spare parts, qualified technicians, service infrastructure — can be significantly higher relative to vehicle operating revenue than in developed markets. Electric powertrains, with fewer moving parts and more predictable service requirements, reduce the exposure to the maintenance cost volatility that characterises conventional fleet operation in markets with less developed automotive service ecosystems.
Section 3: Ride-Hailing as an Electrification Accelerator
The expansion of app-based ride-hailing platforms across emerging markets has created a new commercial fleet segment that is, in several respects, more amenable to rapid electrification than traditional taxi fleets.
Fleet concentration is the first factor. Ride-hailing platforms in emerging markets have, in many cases, accelerated the transition from individually-owned taxis to professionally managed fleet operations. Larger fleet operators — who own and manage dozens or hundreds of vehicles — have the scale to justify investment in depot charging infrastructure, fleet management software and the operational processes that make electrification work efficiently. Individual owner-operators, by contrast, face higher barriers to electrification due to the capital requirements and operational complexity involved.
Platform incentive alignment is the second factor. Ride-hailing platforms operating in emerging markets have commercial incentives to support fleet electrification — lower operating costs for fleet partners improve platform economics, and zero-emission vehicle commitments are increasingly relevant to the institutional investors and corporate clients that platforms depend on. Several major ride-hailing platforms have announced fleet electrification programmes in emerging markets, creating structured pathways for fleet operators to access vehicles, financing and charging infrastructure.
Driver economics in ride-hailing contexts create a direct personal incentive for electrification. Drivers who own or lease their vehicles and bear their own fuel and maintenance costs have a direct financial interest in reducing those costs. In markets where fuel costs represent a significant proportion of gross earnings, the operating cost reduction from electrification translates directly into improved driver income — a powerful adoption incentive that operates independently of regulatory pressure.
Data infrastructure that ride-hailing platforms have built — GPS tracking, trip data, driver behaviour analytics — provides the operational foundation for fleet electrification management. Fleet operators who already have visibility into vehicle utilisation, route patterns and driver behaviour are better positioned to plan charging schedules, optimise vehicle deployment and manage battery health than those operating without data infrastructure.
Section 4: Fleet Replacement Cycles — A Structural Opportunity
Commercial vehicle fleets in emerging markets are, in many cases, older on average than their developed-market counterparts. Extended replacement cycles — driven by capital constraints, import duty structures and the absence of domestic manufacturing — mean that a significant proportion of the commercial taxi fleet in many emerging market cities consists of vehicles that are approaching or have exceeded their optimal operational life.
This creates a structural replacement opportunity that coincides with the improving economics and availability of electric commercial vehicles.
The replacement decision point — when a fleet operator must choose between continuing to operate an ageing conventional vehicle, replacing it with a new conventional vehicle, or transitioning to an electric alternative — is the moment at which the economics of electrification are most directly relevant. Fleet operators who are already facing replacement decisions are evaluating electric options against the full cost of new conventional vehicle acquisition, not against the sunk cost of an existing fleet.
Import duty structures in many emerging markets have historically made vehicle acquisition expensive, extending replacement cycles beyond what would be economically optimal. Governments that reduce or eliminate import duties on electric commercial vehicles — or that establish preferential financing for fleet electrification — can accelerate replacement cycles while simultaneously shifting the composition of new fleet acquisitions toward electric vehicles.
Leapfrog dynamics are a genuine feature of emerging market technology adoption. Markets that are building or rebuilding commercial fleet infrastructure from a lower base have the opportunity to adopt current-generation technology rather than incrementally upgrading from legacy systems. The same dynamic that enabled mobile payment adoption in markets that lacked established banking infrastructure applies, in principle, to fleet electrification in markets that are expanding their commercial vehicle fleets rather than replacing mature ones.
Section 5: Government Investment and Smart City Programmes
The policy environment for fleet electrification in emerging markets is evolving rapidly, driven by a combination of air quality concerns, energy security considerations and the ambition to participate in the global transition to electric mobility.
Air quality is the most immediate policy driver in many emerging market cities, where rapid motorisation has created severe urban air pollution with direct public health consequences. Governments that have committed to air quality improvement targets — under domestic pressure or international agreements — have a direct policy interest in accelerating the electrification of the commercial vehicle fleets that contribute disproportionately to urban emissions.
Energy security considerations are particularly relevant in markets that are significant net importers of petroleum products. Fleet electrification reduces dependence on imported fuel, improves the trade balance and insulates the domestic economy from global oil price volatility. For governments managing foreign exchange constraints, the energy security argument for fleet electrification has a fiscal dimension that goes beyond environmental policy.
Smart city programmes in a number of emerging economies are incorporating electric mobility as a core component of urban infrastructure planning. New city developments, transport corridor projects and urban renewal programmes are increasingly designed with electric vehicle infrastructure — charging networks, smart traffic management, integrated mobility platforms — as a baseline specification rather than a future addition. Fleet operators who electrify in alignment with these programmes gain access to infrastructure investment that reduces their own capital requirements.
International development finance for clean transport projects in emerging markets has expanded significantly, with multilateral development banks, bilateral development agencies and green climate funds providing concessional financing for fleet electrification programmes. This external capital reduces the cost of fleet electrification for both governments and private fleet operators in markets where domestic capital is constrained.
Section 6: Charging Infrastructure — Building From a Different Starting Point
The charging infrastructure challenge in emerging markets is real but is sometimes overstated as a barrier to fleet electrification. The relevant comparison is not between emerging market charging infrastructure and developed-market charging infrastructure — it is between emerging market charging infrastructure and the fuel supply infrastructure that commercial fleets currently depend on.
Depot charging — the installation of charging equipment at fleet operating bases — does not require a public charging network. A fleet operator who controls a depot with reliable grid access can install charging infrastructure that serves the entire fleet without depending on public infrastructure at all. For professionally managed fleet operations, depot charging is the primary charging strategy, and its feasibility depends on grid access and capital availability rather than on the density of public charging points.
Solar-supplemented charging is particularly relevant in emerging markets with high solar irradiance — which describes a large proportion of the markets where fleet electrification opportunity is greatest. Fleet operators who combine grid charging with rooftop or canopy solar generation reduce their energy costs further and reduce their exposure to grid reliability issues.
Grid reliability is a genuine operational challenge in markets where power supply is intermittent. Fleet operators in these markets need to plan charging schedules around grid availability, invest in battery storage to buffer supply variability, or operate with charging infrastructure that can function effectively on partial grid access. These are real operational challenges, but they are manageable with appropriate planning and infrastructure investment — and they are being addressed progressively as grid infrastructure improves.
The infrastructure build-out trajectory in many emerging markets is accelerating, driven by the same combination of government investment, international development finance and private sector deployment that is expanding grid access and renewable energy capacity. Fleet operators who electrify now are building operational experience with charging infrastructure that will become progressively more capable and reliable over the operational life of their current fleet.
Section 7: What Purpose-Built Commercial EVs Mean for Emerging Markets
The vehicle specification requirements of commercial taxi operations in emerging markets differ in important respects from those of developed-market fleet applications — and these differences have direct implications for which vehicles are genuinely suited to these markets.
Climate resilience is a primary requirement in markets where ambient temperatures regularly exceed the conditions under which most consumer EVs are optimised. Battery thermal management systems, climate control capacity and component specifications need to be appropriate for sustained operation in hot, humid or dusty conditions rather than for temperate environments.
Road condition tolerance is relevant in markets where road surfaces are variable and where vehicles encounter conditions — unpaved roads, significant potholes, water crossings — that are uncommon in developed-market urban environments. Suspension specifications, ground clearance and structural durability need to reflect these operating conditions.
LHD and RHD availability is a basic market access requirement. A significant proportion of the highest-growth emerging markets — including much of sub-Saharan Africa, South and Southeast Asia and parts of the Middle East — require right-hand drive vehicles. Manufacturers who offer commercial fleet vehicles in both configurations have access to a substantially larger addressable market than those who do not.
Service network localisation — the availability of trained technicians, spare parts and service support in the specific markets where vehicles are deployed — is a practical requirement that affects operational viability. Vehicles that are well-supported in their home markets but lack service infrastructure in emerging market deployment locations create operational risk that fleet operators cannot easily manage.
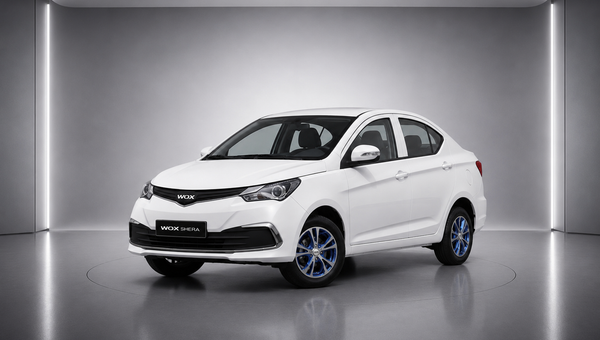
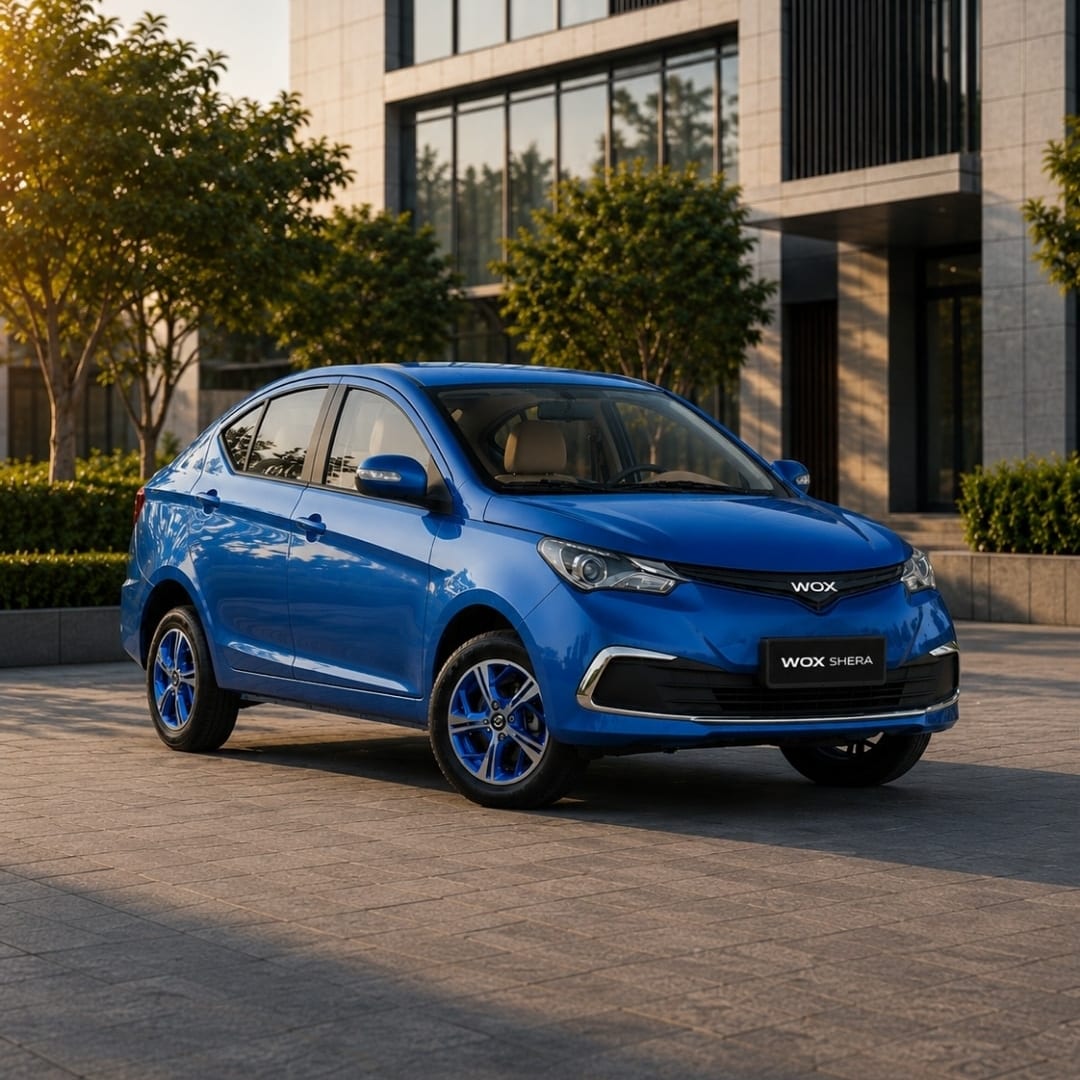
The WOX Shera is one example of a commercial fleet vehicle developed with these emerging market requirements as primary design considerations — available in both LHD and RHD configurations, specified for diverse climate conditions, and built on a commercial platform designed for the operating demands of professional taxi and fleet use across a range of markets. It illustrates the direction that purpose-built commercial EV development is taking in response to the specific requirements of emerging market fleet operators — though the right vehicle for any specific operation depends on the full range of factors discussed in this article.
Conclusion: The Next Wave Is Already Forming
The narrative of fleet electrification as a developed-market phenomenon is being overtaken by events. The structural conditions that drive commercial fleet electrification — fuel cost pressure, urban growth, fleet replacement cycles, government investment and the improving economics of electric vehicles — are present in emerging markets in forms that are, in several respects, more compelling than their developed-market equivalents.
The transition will not be uniform. Different markets will move at different speeds, shaped by their specific policy environments, infrastructure conditions, capital availability and fleet composition. But the direction is consistent: the commercial taxi and ride-hailing fleets that serve the rapidly growing cities of Africa, Asia and Latin America are among the most economically motivated candidates for electrification in the global fleet market.
The operators, manufacturers and investors who recognise this early — and who build the vehicles, infrastructure and operational models suited to these markets — are positioning themselves at the leading edge of what may prove to be the largest fleet electrification opportunity of the coming decade.
Explore WOX Motor's commercial fleet solutions: WOX Shera · Fleet Solutions · Charging Infrastructure · EV Technology · Knowledge Centre · Newsroom