How Governments Are Supporting Taxi Fleet Electrification
Across developed and emerging markets alike, governments are increasingly treating taxi fleet electrification not as an environmental aspiration but as a policy priority — deploying incentives, regulatory frameworks and infrastructure investment to accelerate the transition.
The electrification of taxi fleets is not happening in a policy vacuum. Across developed and emerging markets, governments at national, regional and municipal levels are actively shaping the conditions under which commercial fleet operators make vehicle procurement decisions — through incentive structures, regulatory requirements, infrastructure investment and, increasingly, formal public-private partnerships.
Understanding the policy environment is not a peripheral concern for fleet operators. The financial case for electrification, the timeline for compliance with emissions regulations, the availability of charging infrastructure and the terms on which fleet financing is accessible are all directly influenced by policy decisions. Operators who understand the policy landscape are better positioned to plan fleet transitions strategically rather than reactively.
This article examines the principal mechanisms through which governments are supporting taxi fleet electrification, the rationale behind these interventions, and the implications for fleet operators navigating the transition.
Section 1: Why Do Governments Prioritise Taxi Fleet Electrification?
The policy interest in taxi fleet electrification is not primarily about taxis. It is about air quality, carbon emissions and the broader challenge of decarbonising urban transport — and taxis happen to be a particularly effective lever for addressing all three.
Air quality is the most immediate driver in many urban markets. Road transport is a significant contributor to nitrogen dioxide and particulate matter concentrations in urban areas, and the health consequences — respiratory disease, cardiovascular conditions, reduced life expectancy — impose substantial costs on public health systems. Taxi fleets, which operate intensively in urban cores where pedestrian and residential exposure is highest, contribute disproportionately to localised air quality problems relative to their share of total vehicle kilometres.
Electrifying taxi fleets therefore delivers air quality benefits that are concentrated precisely where they matter most — in the dense urban environments where pollution exposure is highest and where the health burden is most acute. This spatial concentration of benefit makes taxi fleet electrification a high-return intervention from a public health perspective.
Carbon reduction is the second major driver. Transport is typically one of the largest sectoral contributors to national greenhouse gas inventories, and road transport accounts for the majority of transport emissions. Commercial vehicle fleets — which cover significantly more kilometres per year than private cars — represent a disproportionate share of road transport emissions relative to their numbers. Electrifying commercial fleets therefore delivers carbon reductions that are larger per vehicle than equivalent private car electrification.
Urban sustainability goals — reducing congestion, improving liveability, meeting net-zero commitments — are increasingly embedded in city-level planning frameworks. Taxi fleet electrification contributes to multiple dimensions of these goals simultaneously: reducing emissions, improving air quality, demonstrating the viability of commercial EV deployment, and building the charging infrastructure that supports broader electrification.
Fleet modernisation is a secondary but genuine policy interest. Older commercial vehicle fleets — particularly in emerging markets where vehicle replacement cycles are long — represent a significant source of both emissions and road safety risk. Government programmes that accelerate fleet renewal achieve modernisation benefits that extend beyond electrification alone.
Section 2: What Incentive Mechanisms Are Governments Using?
The incentive toolkit available to governments for accelerating taxi fleet electrification is broad, and different jurisdictions have deployed different combinations depending on their fiscal capacity, policy priorities and market conditions.
Purchase incentives — grants, subsidies or tax credits that reduce the upfront acquisition cost of electric vehicles — are among the most widely used mechanisms. The rationale is straightforward: electric vehicles typically carry higher upfront costs than conventional equivalents, even where total cost of ownership is favourable. Purchase incentives bridge this gap, making the economics of electrification accessible to fleet operators who might otherwise be deterred by capital constraints.
Commercial fleet operators often qualify for enhanced purchase incentive rates relative to private buyers, reflecting the policy priority attached to fleet electrification and the larger emissions reduction potential of commercial vehicles. The specific terms vary significantly by jurisdiction, but the directional intent — reducing the financial barrier to fleet electrification — is consistent.
Tax incentives take various forms: accelerated depreciation for electric commercial vehicles, reduced vehicle registration taxes, exemptions from road user charges, or preferential treatment under corporate tax frameworks. These mechanisms reduce the effective cost of fleet electrification over the vehicle's operational life rather than at the point of purchase, and are particularly relevant for fleet operators with significant tax positions.
Operating cost incentives include reduced electricity tariffs for commercial fleet charging, preferential access to bus lanes and low-emission zones, reduced or waived congestion charges, and priority licensing for electric taxi operators. These incentives improve the economics of electric fleet operation on an ongoing basis rather than simply at the point of acquisition.
Scrappage schemes — programmes that provide financial incentives for retiring older, higher-emission vehicles — are used in some markets to accelerate fleet renewal while simultaneously removing the most polluting vehicles from circulation. For fleet operators with ageing conventional fleets, scrappage schemes can materially improve the economics of transitioning to electric vehicles.
Section 3: How Are Regulatory Frameworks Shaping Fleet Electrification Timelines?
Alongside financial incentives, regulatory frameworks are increasingly defining the timeline within which fleet electrification is not optional but required. For fleet operators, understanding the regulatory trajectory is as important as understanding the incentive landscape — because compliance timelines determine when investment decisions must be made.
Low-emission zones — geographic areas within which vehicles must meet specified emissions standards to operate — are among the most direct regulatory instruments affecting taxi fleets. Cities that have established low-emission zones with progressively tightening standards create a clear compliance timeline for fleet operators: electrify by a specified date or lose the right to operate in the zone. For taxi operators whose business depends on access to urban cores, this is a powerful incentive.
Zero-emission vehicle mandates for taxi licensing are a more targeted instrument. Some jurisdictions have established requirements that new taxi licences, or licence renewals, must be for zero-emission vehicles from a specified date. This creates a natural fleet renewal pathway: as licences come up for renewal, operators must transition to electric vehicles to maintain their operating rights.
Fleet emissions standards — requirements that commercial fleets meet specified average emissions levels — create compliance obligations that can be met through a combination of vehicle electrification and fleet management. For larger fleet operators, these standards create a portfolio-level incentive to electrify the highest-utilisation vehicles first, where the emissions reduction per vehicle is greatest.
Procurement requirements for publicly contracted taxi services — airport transfers, hospital transport, government fleet contracts — increasingly specify zero-emission vehicles as a condition of contract. For fleet operators who supply these services, compliance is a commercial requirement rather than a regulatory one, but the effect on fleet composition is the same.
The cumulative effect of these regulatory instruments is to create a progressively narrowing window within which conventional taxi fleet operation remains commercially viable in regulated markets. Fleet operators who plan their electrification timelines around regulatory requirements — rather than waiting for compliance deadlines — are better positioned to manage the transition without operational disruption.
Section 4: Infrastructure Investment — The Public Role in Enabling Fleet Electrification
Financial incentives and regulatory requirements can accelerate fleet electrification decisions, but they cannot substitute for the physical infrastructure that makes electric fleet operation viable. Charging infrastructure — particularly the depot charging facilities and public fast charging networks that commercial fleets depend on — requires capital investment that individual fleet operators cannot always provide alone.
Governments are increasingly recognising this infrastructure gap and deploying public investment to address it, through several mechanisms.
Direct infrastructure grants fund the installation of charging infrastructure at fleet depots, taxi ranks, transport hubs and other locations where commercial vehicles concentrate. These grants reduce the capital cost of infrastructure deployment for fleet operators and accelerate the build-out of the charging network that commercial electrification requires.
Grid connection support addresses one of the most significant practical barriers to depot charging deployment: the cost and complexity of upgrading electrical grid connections to support the aggregate charging demand of a commercial fleet. In some markets, government programmes subsidise grid connection upgrades for fleet operators, removing a barrier that can otherwise make depot charging economically prohibitive.
Public charging network investment — funding for fast charging infrastructure on public roads, at transport hubs and in urban centres — supports the opportunity charging that commercial fleets use to supplement depot charging. Government investment in public charging infrastructure reduces the operational risk of fleet electrification by ensuring that vehicles can access charging when they are away from depot.
Land allocation for charging infrastructure — designating sites at taxi ranks, transport interchanges and urban car parks for commercial charging facilities — is a non-financial but practically important form of government support. In dense urban environments where land is scarce and expensive, government allocation of suitable sites can be as valuable as direct financial support.
Section 5: Public-Private Partnerships — Sharing Risk and Accelerating Deployment
The scale of investment required to electrify commercial taxi fleets — across vehicles, charging infrastructure, grid connections and fleet management systems — exceeds what either the public or private sector can efficiently deploy alone. Public-private partnerships (PPPs) are increasingly used to share risk, combine capabilities and accelerate deployment at a scale that neither party could achieve independently.
Fleet financing partnerships between government agencies and financial institutions provide fleet operators with access to capital on terms that reflect the policy priority attached to electrification. Government-backed loan guarantees, green finance facilities and blended finance structures reduce the cost of capital for fleet electrification investments, making the economics more accessible for operators who face financing constraints.
Charging infrastructure concessions — arrangements in which private operators invest in and manage charging infrastructure in exchange for operating rights and, in some cases, government revenue guarantees — enable the deployment of commercial charging networks without requiring full public funding. These arrangements align private investment incentives with public infrastructure goals, accelerating deployment while managing public expenditure.
Pilot programmes — structured collaborations between government agencies, vehicle manufacturers and fleet operators to test and demonstrate electric fleet operation in real-world commercial conditions — serve multiple functions. They generate operational data that informs policy design, demonstrate the viability of electric fleet operation to sceptical operators, and identify infrastructure and regulatory barriers that need to be addressed before large-scale deployment.
Manufacturer engagement is an increasingly important dimension of public-private partnership in fleet electrification. Governments that engage directly with vehicle manufacturers — establishing procurement frameworks, co-funding product development for specific market requirements, or creating regulatory environments that reward purpose-built commercial EV development — can accelerate the availability of vehicles that meet the specific needs of commercial fleet operators.
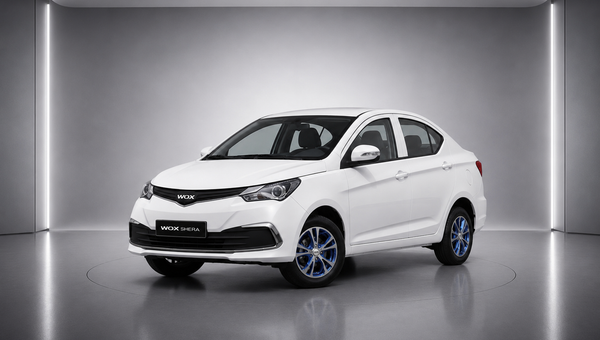
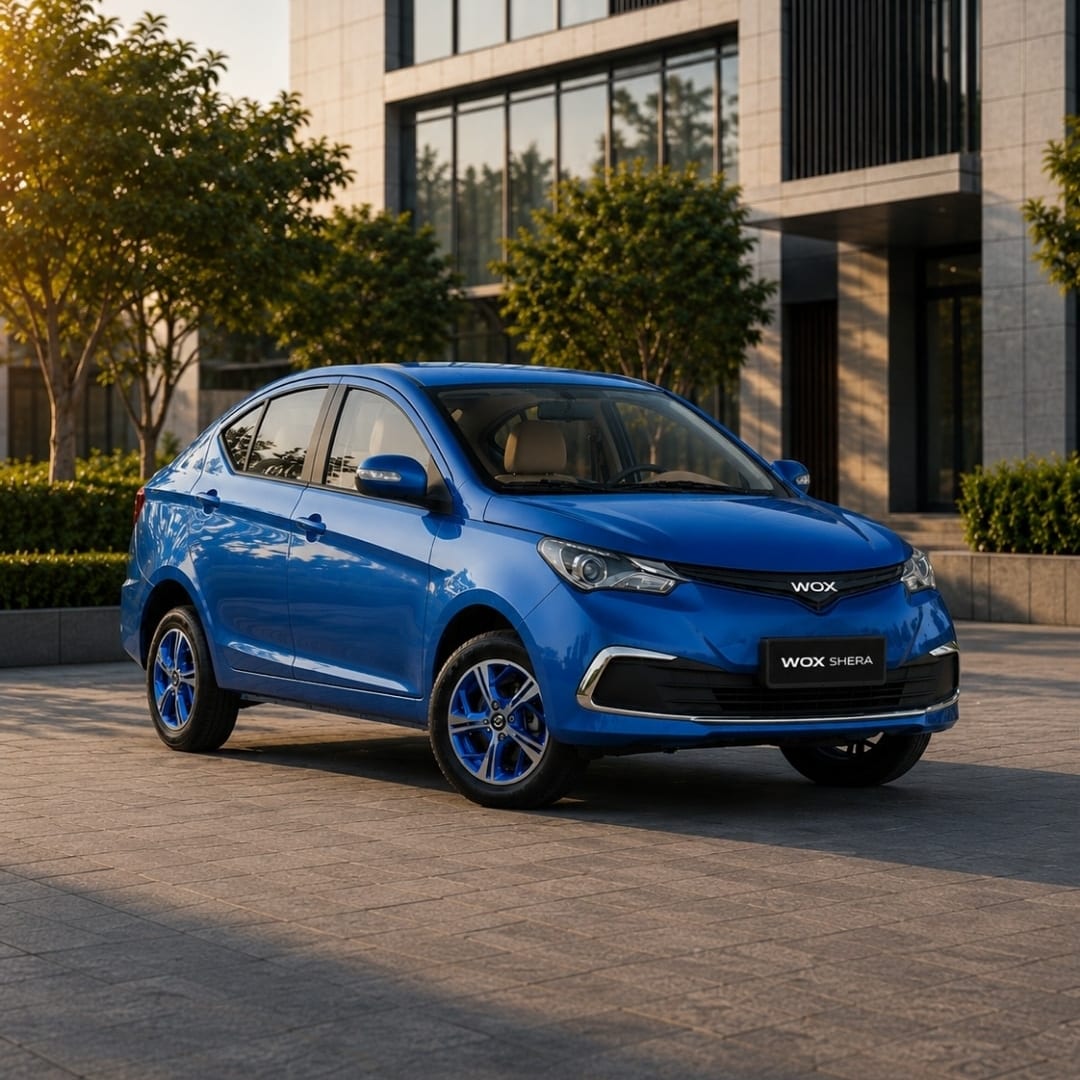
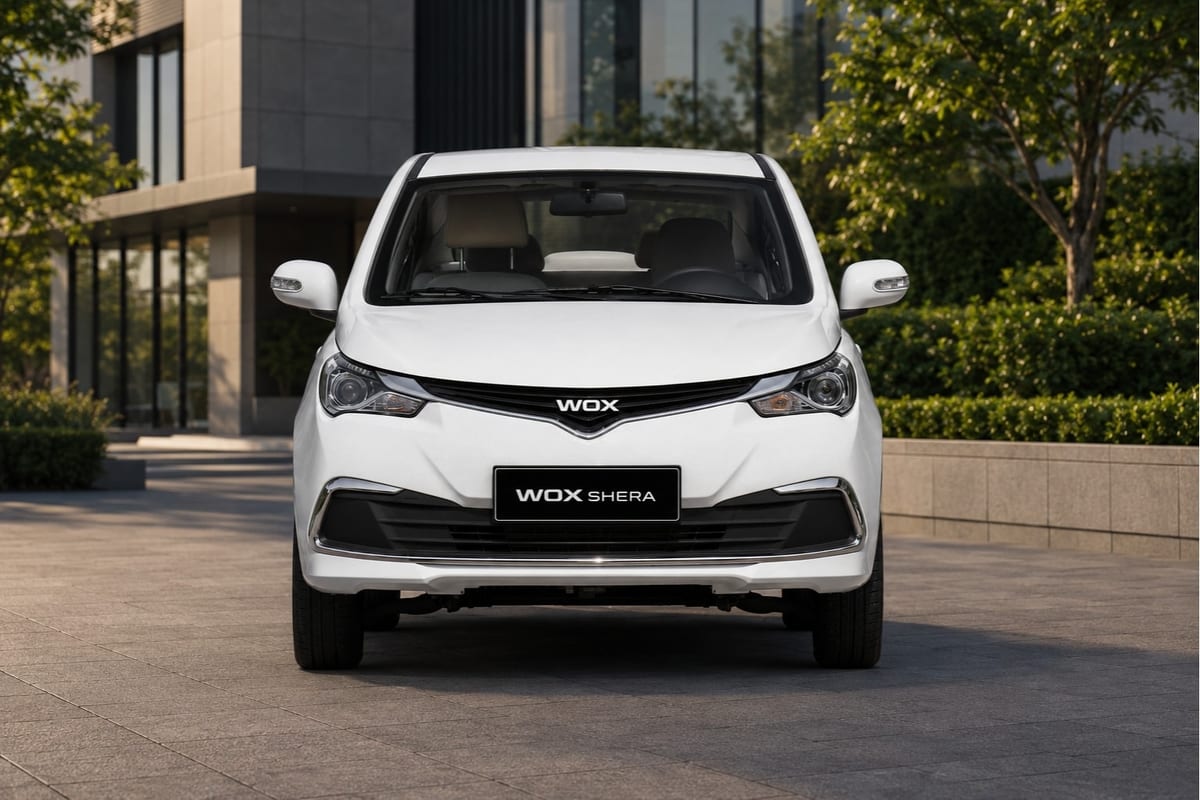
This is relevant to the broader direction of commercial EV development. Vehicles like the WOX Shera — designed from the outset for professional taxi and commercial fleet operations, with LHD and RHD configurations for different market requirements and an architecture suited to high-utilisation commercial deployment — reflect the kind of purpose-built commercial EV development that government-manufacturer engagement is increasingly designed to encourage. The policy environment is creating demand for vehicles that meet commercial fleet requirements; manufacturers who respond to that demand with purpose-built solutions are better positioned to participate in the fleet electrification programmes that governments are funding.
Section 6: Emerging Markets — A Different Policy Context
The policy environment for taxi fleet electrification in emerging markets differs in important respects from that in developed economies, and the differences have direct implications for fleet operators and manufacturers operating in these markets.
Fiscal constraints limit the scale of direct financial incentives available in many emerging markets. Governments with limited fiscal capacity cannot deploy the purchase subsidy programmes that have accelerated fleet electrification in wealthier markets. The policy toolkit in these contexts tends to rely more heavily on regulatory instruments — emissions standards, low-emission zone designations, licensing requirements — and on attracting private investment through concessional frameworks rather than direct grants.
Infrastructure gaps are more significant in emerging markets, where public charging networks are sparse and grid reliability may be variable. Government investment in charging infrastructure is therefore a higher priority in these markets, and the public-private partnership models used to deploy it need to account for higher infrastructure risk.
Import duty structures significantly affect the economics of electric vehicle adoption in markets where EVs are imported. Governments that reduce or eliminate import duties on electric commercial vehicles — or that establish domestic manufacturing incentives that reduce vehicle costs — can materially improve the financial case for fleet electrification without direct subsidy expenditure.
Leapfrog potential is a genuine opportunity in emerging markets. Cities that are still developing their transport infrastructure — building new taxi licensing frameworks, establishing urban mobility regulations, planning charging infrastructure — have the opportunity to design these systems with electrification as the default rather than retrofitting electrification onto frameworks designed for conventional vehicles. Governments that recognise this opportunity and act on it can accelerate fleet electrification timelines significantly relative to markets where legacy infrastructure and regulatory frameworks create transition friction.
Conclusion: Policy as a Strategic Input for Fleet Operators
The policy environment for taxi fleet electrification is not static. Incentive programmes are introduced, modified and withdrawn. Regulatory timelines are set and sometimes accelerated. Infrastructure investment priorities shift. The operators who treat policy as a strategic input — monitoring the regulatory trajectory, engaging with incentive programmes proactively, and planning fleet transitions around compliance timelines rather than waiting for deadlines — are better positioned to manage the transition efficiently.
The direction of travel is clear. Governments across developed and emerging markets are treating taxi fleet electrification as a policy priority, and the combination of financial incentives, regulatory requirements and infrastructure investment they are deploying is progressively improving the economics of the transition while narrowing the window within which conventional fleet operation remains viable.
For fleet operators, the question is not whether to electrify but how to do so in a way that captures the available policy support, manages the transition risks, and positions the fleet for the operating environment that is being created — not the one that currently exists.
Explore WOX Motor's commercial fleet solutions: WOX Shera · Fleet Solutions · Charging Infrastructure · EV Technology · Knowledge Centre · Newsroom