The Future of Urban Taxi Mobility
Cities are changing faster than the vehicles that serve them. As urbanisation accelerates, shared mobility expands and electric powertrains become the commercial standard, the taxi is not disappearing — it is evolving into something more integrated, more efficient and more central to the urban mobility ecosystem than it has ever been.
The taxi has existed in some form for over a century. It has survived the automobile, the motorway, the suburban sprawl, the smartphone and the rise of app-based ride-hailing. Each of these transitions was predicted, by someone, to make the taxi obsolete. None of them did.
The current transition — driven by urbanisation, electrification, connectivity and the gradual emergence of autonomous mobility — is more profound than any that preceded it. But the conclusion is the same: the taxi is not disappearing. It is being redefined. And the operators, manufacturers and city planners who understand what it is being redefined into will be better positioned to navigate what comes next.
This article examines the forces reshaping urban taxi mobility, the technologies enabling that transformation, and the role that professional taxi services are likely to play in the cities of the coming decade.
Section 1: How Is Urbanisation Changing the Demand for Taxi Services?
The world is urbanising at a pace that has no historical precedent. The United Nations projects that by 2050, approximately two-thirds of the global population will live in urban areas — a shift that will add billions of people to cities that are already under significant mobility pressure.
This demographic reality has direct consequences for urban transport. As cities grow denser, the private car becomes progressively less practical as a primary mobility solution. Parking scarcity, congestion, air quality regulation and the sheer spatial inefficiency of single-occupancy vehicle use are driving policy responses — congestion charges, low-emission zones, parking restrictions — that make private car ownership less attractive in urban cores.
The beneficiaries of this shift are shared mobility services: public transport, cycling infrastructure, micro-mobility and, critically, professional taxi and ride-hailing services. In dense urban environments, a well-utilised taxi or ride-hailing vehicle can replace multiple private cars in terms of the mobility it provides per unit of road space consumed. This is not a marginal efficiency gain — it is a structural advantage that urban planners are increasingly recognising and, in some cases, actively incentivising.
Emerging market cities present a particularly significant dimension of this trend. Across Africa, South and Southeast Asia, and Latin America, urban populations are growing rapidly in cities where public transport infrastructure is still developing. In these environments, taxi and ride-hailing services often function as the primary formal mobility layer — filling gaps that metro systems, bus rapid transit and light rail cannot yet cover. The electrification of these fleets is therefore not simply an environmental question; it is a question of urban mobility access at scale.
Section 2: What Is Shared Mobility, and Why Does It Matter for Taxis?
Shared mobility — the use of transport assets by multiple users, either simultaneously or sequentially — is one of the defining concepts of contemporary urban transport planning. It encompasses everything from public bus services to bicycle-sharing schemes, from carpooling platforms to on-demand minibus services.
Taxis and ride-hailing vehicles occupy a specific and important position within the shared mobility spectrum. They offer the flexibility and door-to-door convenience of private car travel with the asset utilisation efficiency of a shared service. A taxi that completes twelve journeys per day is, in effect, providing the mobility of twelve private car trips from a single vehicle — with proportionally lower road space consumption, parking demand and, in the case of electric taxis, energy use per passenger kilometre.
The integration of taxi services with other shared mobility modes is an emerging priority for city transport authorities. In several European and Asian cities, taxi and ride-hailing services are being formally integrated into multimodal journey planning platforms — appearing alongside metro, bus and cycling options in unified mobility applications. This integration positions professional taxi services not as competitors to public transport but as complementary last-mile and off-peak mobility solutions.
Pooled ride-hailing — where multiple passengers travelling in similar directions share a single vehicle — extends the efficiency argument further. When implemented effectively, pooled services can achieve passenger-per-vehicle ratios that approach those of bus services while maintaining the flexibility and accessibility advantages of on-demand transport. The commercial viability of pooled services depends heavily on vehicle design — specifically, on whether the vehicle's interior can accommodate multiple passengers comfortably across varied journey configurations.
Section 3: How Is EV Adoption Reshaping Commercial Taxi Fleets?
The electrification of taxi fleets is no longer a future scenario — it is an ongoing transition that is progressing at different rates across different markets, driven by a combination of regulatory pressure, economic incentive and improving vehicle technology.
Regulatory drivers are the most immediate force. Low-emission zones in European cities, zero-emission vehicle mandates for taxi licensing in several major markets, and national fleet electrification targets are creating compliance timelines that fleet operators cannot ignore. In London, New York, Amsterdam and an increasing number of other cities, the question for taxi operators is not whether to electrify but when and how.
Economic drivers are becoming increasingly compelling independently of regulation. The total cost of ownership of electric taxis — accounting for lower energy costs, reduced maintenance requirements and, in some markets, preferential licensing or access rights — is increasingly competitive with conventional alternatives, particularly for high-utilisation commercial operations where the energy cost advantage compounds most significantly.
Vehicle technology has reached a level of maturity that makes electric taxis operationally viable for most commercial applications. Range, charging speed and reliability have all improved substantially over the past five years. The remaining barriers — charging infrastructure availability, upfront acquisition cost and service network coverage — are real but diminishing, and are being addressed by a combination of manufacturer investment, government infrastructure programmes and fleet financing innovation.
The electrification of taxi fleets is also creating a new category of vehicle design requirement. Operators who have transitioned to electric vehicles are discovering that the specific demands of commercial taxi operation — high daily utilisation, continuous climate control, frequent passenger boarding, urban stop-start driving — require vehicles engineered for these conditions rather than adapted from consumer platforms. This recognition is driving investment in purpose-built commercial EV platforms across the industry.
Section 4: What Role Will Autonomous Mobility Play in Urban Taxi Services?
Autonomous vehicle technology is one of the most discussed and most frequently misrepresented topics in contemporary transport analysis. A clear-eyed assessment requires distinguishing between what is technically demonstrated, what is commercially deployed at scale, and what remains a development-stage aspiration.
What is currently demonstrated: SAE Level 2 and Level 3 driver assistance systems — including adaptive cruise control, lane-keeping assistance, automated emergency braking and, in some vehicles, hands-free highway driving — are commercially available and increasingly standard in new vehicles. These systems reduce driver fatigue, improve safety outcomes and, in some operating conditions, improve energy efficiency.
What is commercially deployed in limited contexts: SAE Level 4 autonomous operation — vehicles capable of operating without human intervention within a defined geographic area and set of conditions — is commercially deployed in a small number of cities, primarily in the United States and China, by a small number of operators. These deployments are real, but they are geographically constrained, operationally limited and not yet economically self-sustaining at scale.
What remains a development-stage aspiration: Fully autonomous urban taxi operation across the full range of weather conditions, road types, traffic scenarios and regulatory environments that characterise real-world commercial taxi operations in most cities is not yet commercially viable. The technical challenges — particularly in complex urban environments, adverse weather and edge-case scenarios — remain substantial.
The practical implication for fleet operators is that advanced driver assistance systems are a relevant and valuable specification today, while full autonomy is a medium-to-long-term development that will emerge incrementally in specific markets and operating contexts rather than arriving as a sudden transformation. Fleet operators who invest in vehicles with strong ADAS foundations are better positioned to benefit from incremental autonomy improvements as they become available.
Section 5: How Is Ride-Hailing Changing the Taxi Industry?
The emergence of app-based ride-hailing platforms over the past fifteen years has fundamentally altered the competitive landscape of urban taxi services. The effects have been complex and, in some respects, counterintuitive.
The demand expansion effect: In many markets, ride-hailing platforms have expanded the total market for on-demand personal transport rather than simply redistributing existing taxi demand. By reducing friction in the booking process, improving price transparency and extending service availability, platforms have attracted users who previously relied primarily on private cars or public transport. This demand expansion has, in aggregate, increased the total number of commercial vehicle journeys in many urban markets.
The fleet professionalisation effect: Ride-hailing platforms have accelerated the professionalisation of commercial taxi fleets in several respects. Driver rating systems, vehicle condition requirements, real-time tracking and digital payment infrastructure have raised baseline service quality standards across the industry. Operators who have invested in professional fleet management — vehicle maintenance, driver training, service consistency — have generally performed better in the ride-hailing era than those who have not.
The vehicle specification effect: Ride-hailing platforms have created new vehicle specification requirements that are influencing fleet procurement decisions. Passenger comfort ratings, vehicle age limits, accessibility requirements and, increasingly, zero-emission vehicle preferences are shaping the vehicle choices of fleet operators who supply ride-hailing platforms. This is accelerating the transition toward newer, more capable and more sustainable fleet vehicles.
Section 6: What Is Mobility-as-a-Service, and How Does It Affect Taxi Operations?
Mobility-as-a-Service (MaaS) is a concept that describes the integration of multiple transport modes — public transit, taxi, ride-hailing, cycling, micro-mobility — into a single, seamlessly accessible service accessed through a unified digital platform. Rather than purchasing individual transport products (a bus pass, a taxi journey, a bicycle hire), users access a mobility subscription or pay-per-use service that covers all modes.
MaaS is at an early stage of commercial development in most markets. A small number of cities — Helsinki, Vienna, Singapore — have made meaningful progress toward integrated multimodal platforms. Most markets remain fragmented, with different transport modes operating through separate booking systems, payment mechanisms and service standards.
For taxi operators, MaaS represents both an opportunity and a challenge. The opportunity is integration into a broader mobility ecosystem that increases demand visibility and reduces the cost of customer acquisition. The challenge is that MaaS platforms typically require operators to meet specific service standards — vehicle quality, accessibility, reliability, emissions — that may require fleet investment.
Connected vehicle technology is a prerequisite for effective MaaS integration. Vehicles that can communicate real-time location, availability and status data to platform operators enable the dynamic dispatch and journey optimisation that MaaS platforms require. Fleet operators who invest in connected vehicle infrastructure — telematics, fleet management systems, digital dispatch — are better positioned to participate in MaaS ecosystems as they develop.
Section 7: Why Do Taxis Remain Essential in Future Urban Mobility Ecosystems?
The question of whether professional taxi services have a future in an era of autonomous vehicles, shared mobility platforms and expanding public transport is sometimes posed as if the answer might be negative. The evidence suggests otherwise.
Accessibility: Taxis and ride-hailing services provide mobility access for users who cannot or do not use public transport — elderly passengers, people with mobility impairments, passengers with luggage, users travelling at times or to destinations not served by fixed-route services. This accessibility function is not replicated by autonomous vehicles in their current state of development, and is not easily replicated by public transport regardless of its quality.
Flexibility: The on-demand, door-to-door nature of taxi services provides a flexibility that fixed-route public transport cannot match. In cities where public transport coverage is incomplete — which describes most cities in the world — taxis fill critical mobility gaps that would otherwise be served by private cars.
Resilience: Urban mobility systems that depend on a single mode are fragile. When metro systems fail, when extreme weather disrupts cycling infrastructure, when public transport strikes occur, taxi services provide the resilience layer that keeps cities moving. This function is recognised by city transport authorities even where taxi services are not formally integrated into public transport planning.
Economic activity: Taxi services enable economic activity — airport transfers, business travel, late-night hospitality, medical appointments — that is not easily served by other modes. The economic value of this function is difficult to quantify but is substantial in aggregate.
Section 8: What Does the Future Taxi Look Like?
The taxi of the coming decade will differ from its predecessor in several important respects — but it will still be recognisably a taxi.
It will almost certainly be electric. The combination of regulatory pressure, economic incentive and improving vehicle technology makes fleet electrification the default trajectory for commercial taxi operations in most markets over the next ten years.
It will be connected. Real-time telematics, fleet management integration, digital dispatch and, in some markets, MaaS platform connectivity will be standard features rather than optional extras.
It will incorporate advanced driver assistance systems. SAE Level 2 and Level 3 ADAS will become standard specifications for commercial fleet vehicles, improving safety outcomes and, in some operating conditions, energy efficiency.
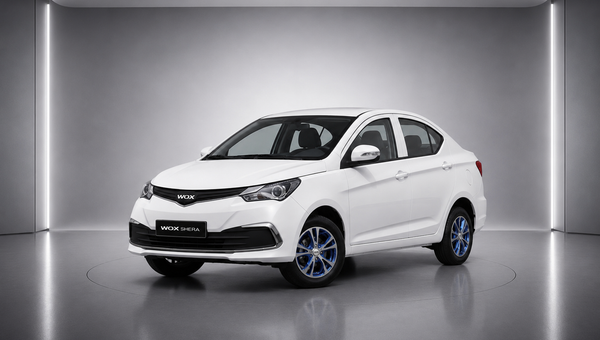
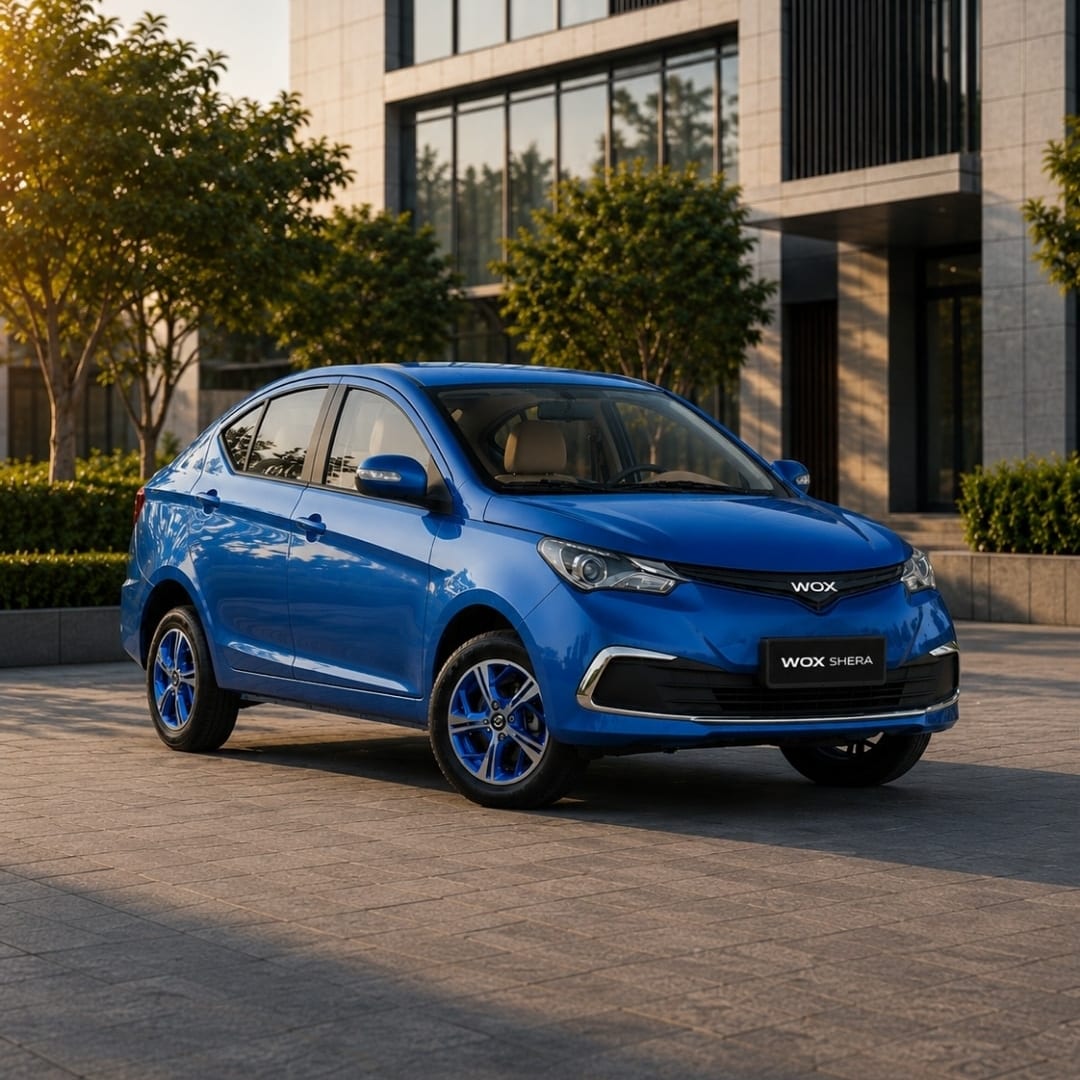
It will be purpose-built for commercial use. The growing recognition that commercial taxi operations require vehicles engineered for their specific demands — rather than adapted from consumer platforms — is driving investment in dedicated commercial EV platforms across the industry. The WOX Shera, designed from the outset for professional taxi and commercial fleet operations with LHD and RHD configurations, SAE Level 2 ADAS and a commercial-grade architecture, is one example of this direction of travel.
And it will be more integrated — with public transport, with shared mobility platforms, with city traffic management systems — than the taxi has ever been before.
Conclusion: The Taxi in the Smart City
The smart city of the coming decade will be defined by the integration of its mobility systems — not by the dominance of any single mode. Public transport, cycling, micro-mobility, autonomous vehicles and professional taxi services will each play a role in a mobility ecosystem that is more efficient, more accessible and more sustainable than what exists today.
In that ecosystem, the taxi's role is not diminished — it is clarified. It is the flexible, accessible, on-demand layer that connects the fixed infrastructure of public transport to the specific mobility needs of individual passengers. It is the resilience layer that keeps cities moving when other systems fail. It is the commercial mobility layer that enables the economic activity that cities depend on.
The operators who will thrive in this environment are those who understand the transition that is underway — who are investing in electric vehicles, connected fleet management, driver training and service quality — and who recognise that the taxi's future is not in competition with the smart city but as an essential component of it.
Explore WOX Motor's commercial fleet solutions: WOX Shera · Fleet Solutions · EV Technology · Charging Infrastructure · Knowledge Centre · Newsroom